The short answer
Insurance for an owner-occupied home and insurance for a rental address different uses and exposures. Tell the insurer how the property is actually occupied and obtain written confirmation of appropriate coverage.
On this page
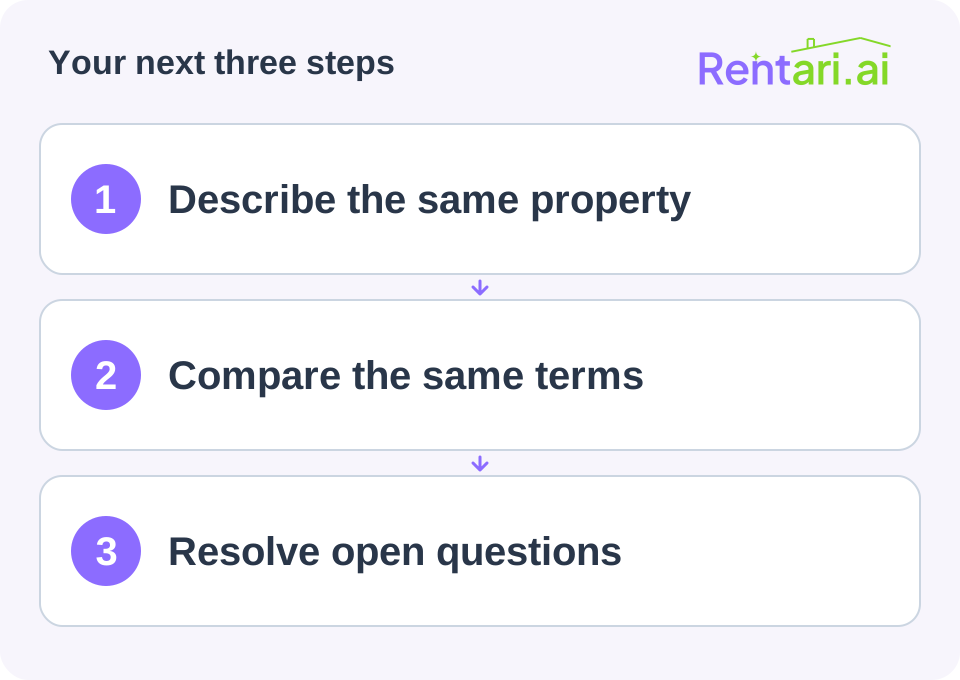
Review the use change
Discuss long-term tenants, short-term stays, vacancies, furnishings and any owner occupancy. Coverage depends on the issued policy and endorsements, not only the product name.
Compare coverage components
Ask about the building, owner-owned contents, liability and covered loss of rental income. Residents generally need their own coverage for their belongings and liability; your policy is not a substitute.
Example: moving out
An owner converts a former home to a full-time rental. Contact the insurer before the change rather than assuming the existing homeowners policy continues to cover the new arrangement.
References and next steps
Use these references for the specific topic they cover. Local requirements and individual circumstances may differ.
The Rentari team writes and updates this guide. Examples illustrate decisions and do not describe customer results. Found an error or an unclear step? Send a correction with a link to this page and the wording you’d change.